AUSTIN, Texas — Tesla looks set to close out the third quarter on a high note, with Barclays telling clients it expects the automaker to beat Wall Street's delivery estimates on the strength of two powerful tailwinds: booming Full Self-Driving adoption and rising exports from Giga Shanghai.
Barclays autos analyst Dan Levy estimates Tesla delivered about 475,000 vehicles in the quarter, above the roughly 466,000 consensus and well ahead of his own prior forecast of 450,000. If that holds, it would keep Tesla tracking toward roughly 1.8 million deliveries for the year — up about 10% from last year and back near its previous peak.
Two Engines Driving the Beat
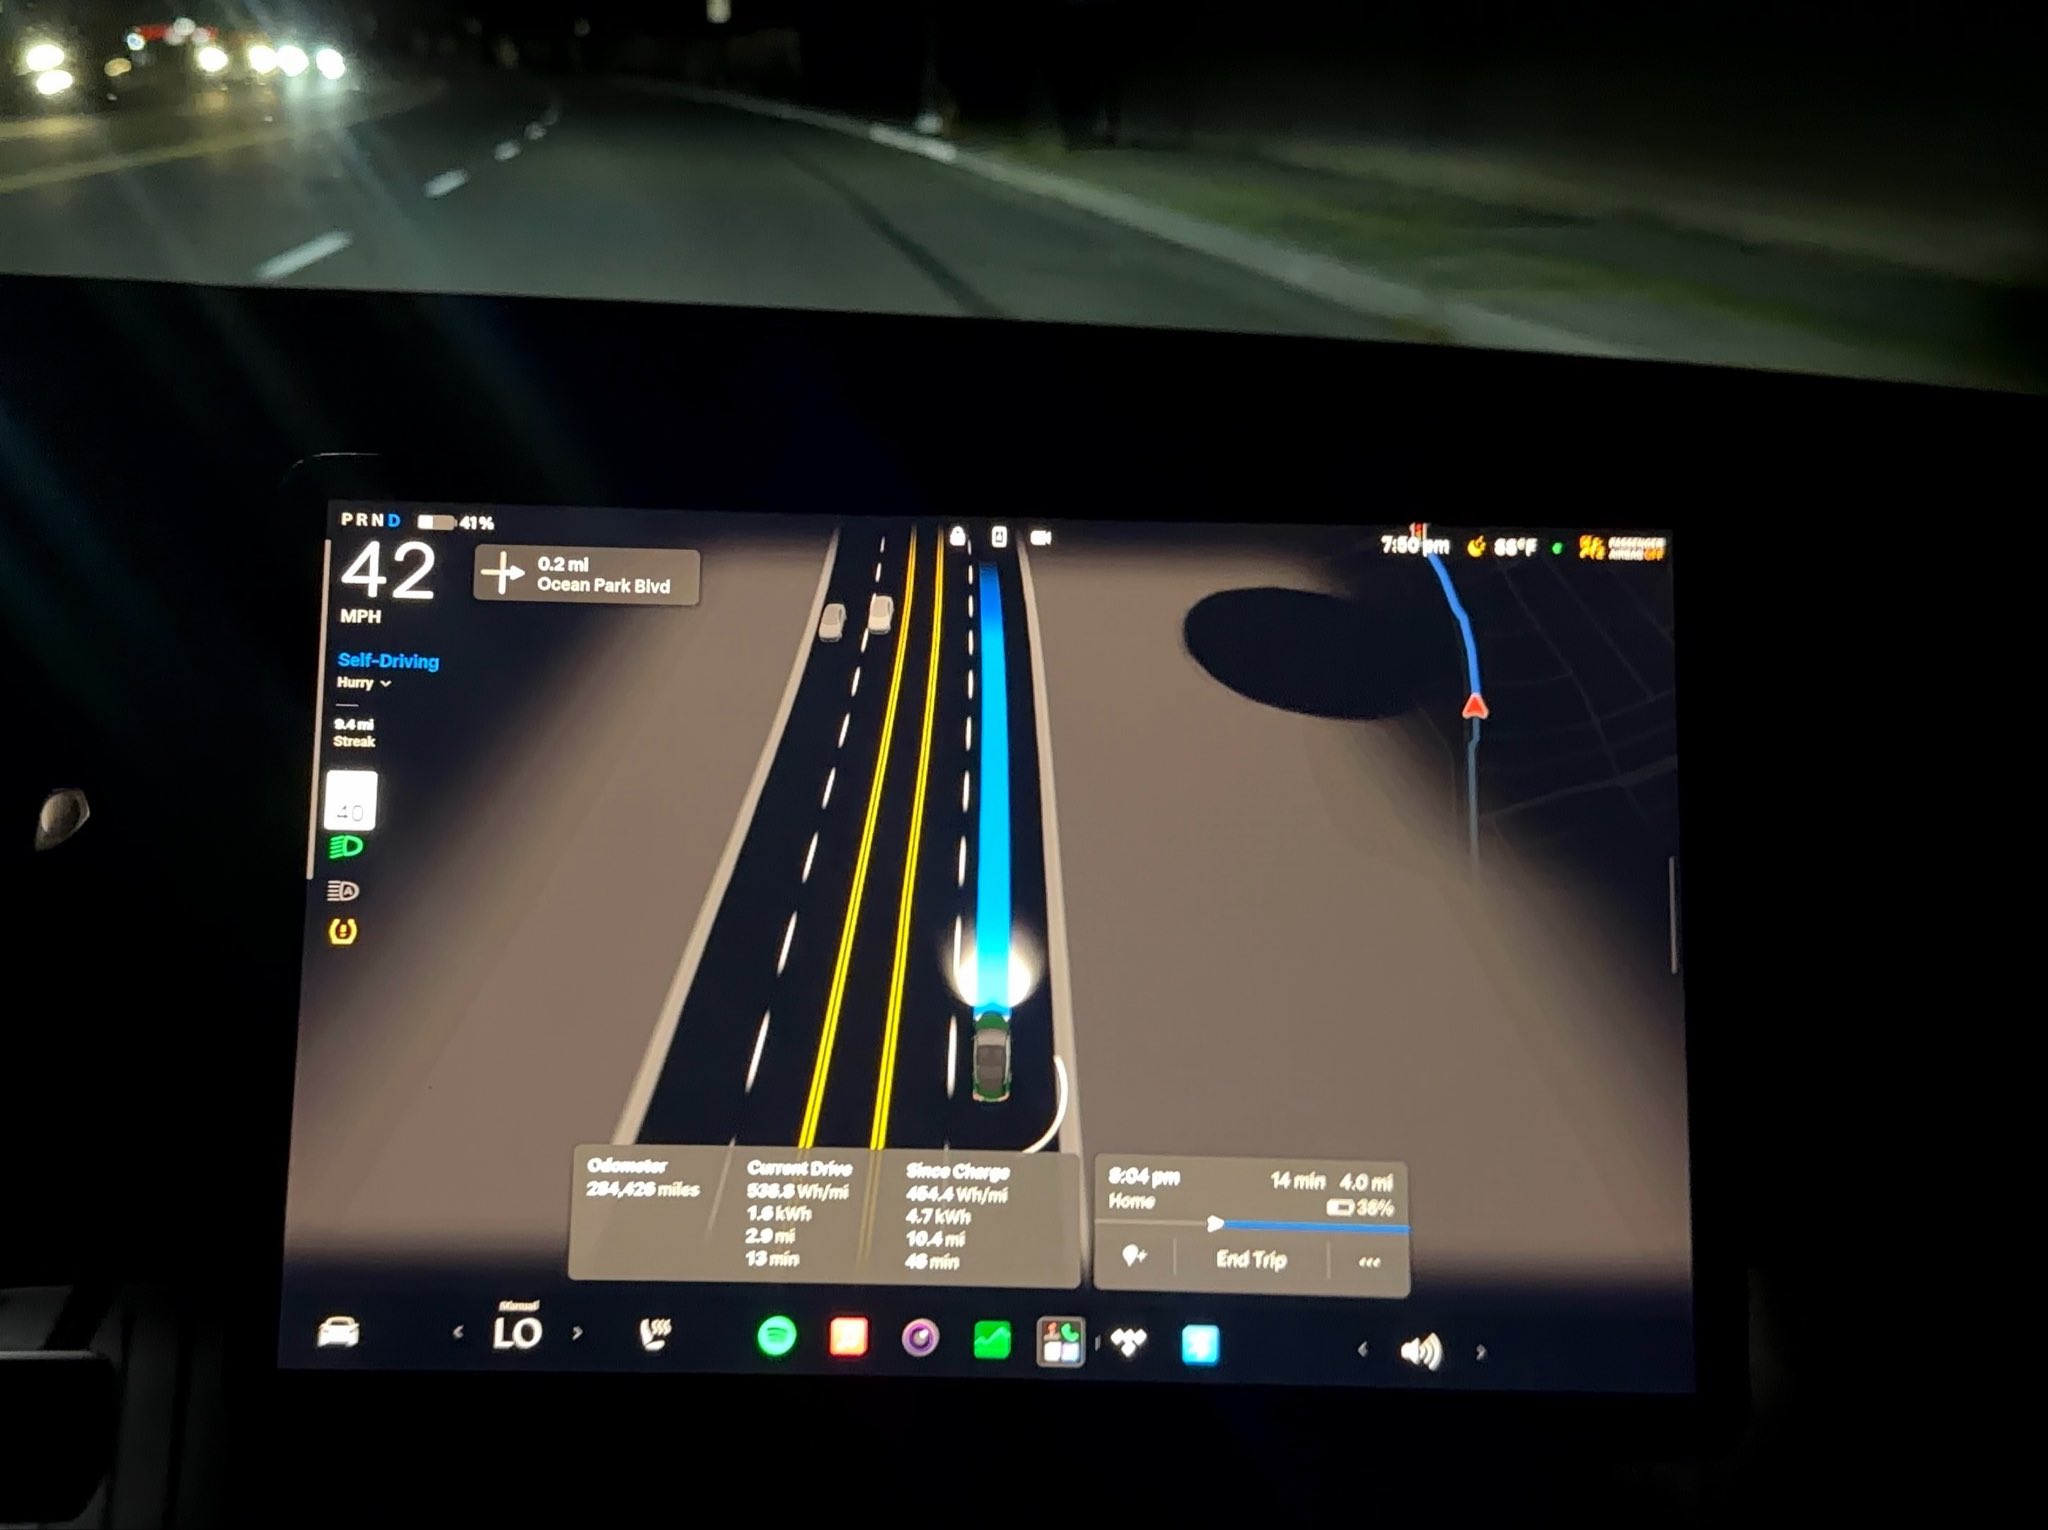
The first driver is Full Self-Driving. Levy notes FSD uptake reached around 55% in the quarter, and argued that buyers are increasingly choosing Tesla specifically because of the software. That matters twice over: FSD lifts margins and, crucially, is now pulling in incremental vehicle volume — turning Tesla's AI investment into showroom demand. The momentum tracks with Tesla's steady software cadence, including the rollout of FSD v14.3.9 with automatic collision evasion.
The second driver is China. After visiting Giga Shanghai, Barclays highlighted Tesla's significant cost advantage there and estimated that exports from Shanghai may account for at least 20% of Tesla's global volume this year. Markets once treated as afterthoughts — Australia, Colombia and parts of Asia — are now delivering meaningful volume, a shift that showed up in Tesla's recent 12-week high in China registrations.
Building on a Strong Second Quarter
The optimism follows a second quarter in which Tesla delivered 480,126 vehicles, crushing expectations, and management flagged its largest order backlog since 2023. That backlog implied room for further growth, and a solid third-quarter print would be another data point confirming that Tesla's volume trajectory has inflected upward after a softer start to the year.